Skip to content
  • Facebook
  • X
  • Linkedin
  • WhatsApp
  • YouTube
  • Associate Journalism
  • About Us
  • Privacy Policy
  • 033-46046046
  • editor@artifex.news
Artifex.News

Artifex.News

Stay Connected. Stay Informed.

  • Breaking News
  • World
  • Nation
  • Sports
  • Business
  • Science
  • Entertainment
  • Lifestyle
  • Toggle search form
  • Typhoon Saudel heads west after pounding Japan’s southwestern remote islands, injuring 2
    Typhoon Saudel heads west after pounding Japan’s southwestern remote islands, injuring 2 World
  • Kremlin says Swiss conference showed futility of talks without Russia
    Kremlin says Swiss conference showed futility of talks without Russia World
  • Access Denied Sports
  • Rs 73 Lakh Assets Attached In Money Laundering Case Against Mukhtar Ansari
    Rs 73 Lakh Assets Attached In Money Laundering Case Against Mukhtar Ansari Nation
  • WHO Chief Tedros Adhanom Ghebreyesus Says “Confident” Of Pandemic Deal Despite Missed Deadline
    WHO Chief Tedros Adhanom Ghebreyesus Says “Confident” Of Pandemic Deal Despite Missed Deadline World
  • Why did a U.S. court stay Trump’s ban on media outlets?
    Why did a U.S. court stay Trump’s ban on media outlets? World
  • Fighting every wildfire makes bigger fires more extreme, study says
    Fighting every wildfire makes bigger fires more extreme, study says Science
  • Citing Tribals, KTR Hits Out At Rahul Gandhi On Caste Census
    Citing Tribals, KTR Hits Out At Rahul Gandhi On Caste Census Nation
RBI’s restrictions on revolving credit | Explained

RBI’s restrictions on revolving credit | Explained

Posted on August 19, 2026 By admin


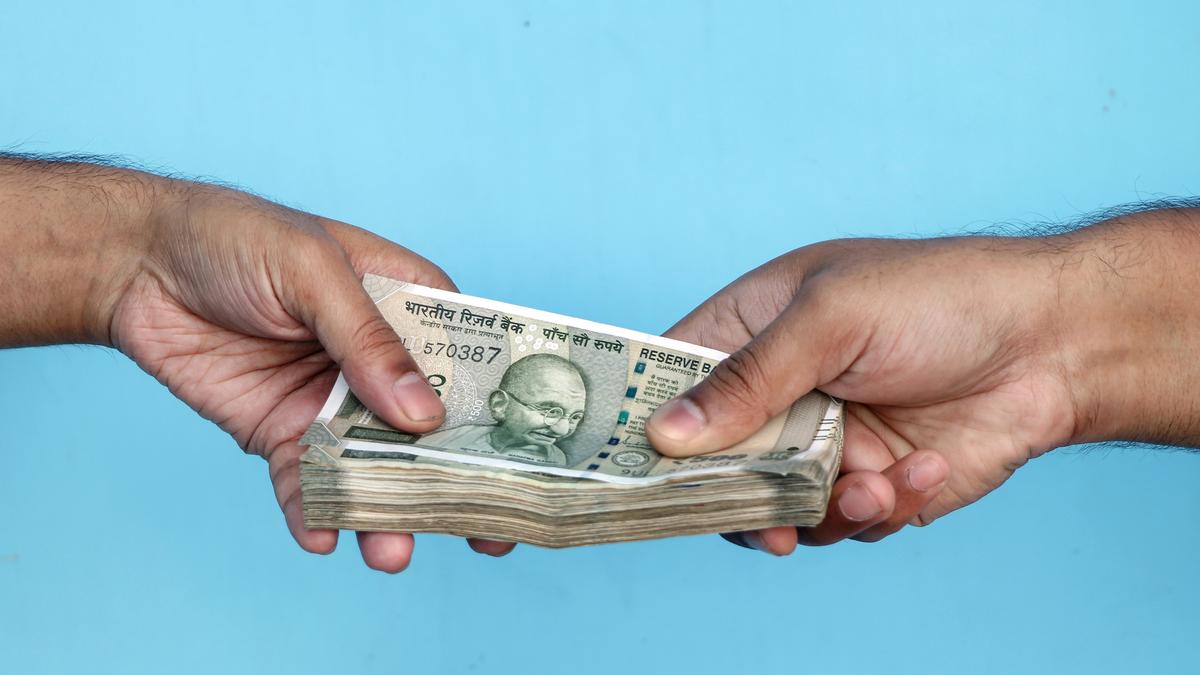
Revolving credit, one of India’s finest tools for financial inclusion, has made deep inroads in creating sustainable rural wealth. Still, rising risks of debt recycling have made the Reserve Bank of India (RBI) sceptical.

For rural India, where income is mainly seasonal and contributes 46% to 50% of gross domestic product, revolving credit became an important component and shield against financial shocks as well as informal loan sharks.

Structural rigidity in the formal credit framework led to mismatch in cash-flow needs of farmers, who incur expenses on seeds, fertilisers, labour and irrigation months ahead of income stream after harvest. Revolving credit bridges this gap by providing liquidity as required.

This led to the emergence of Kisan Credit Card (KCC), overdraft facilities, self-help group (SHG) credit lines, microfinance-linked loans and of late increasingly digital credit products (which is now a cause of concern).

The role of revolving credit extends beyond the farm sector. Rural micro-enterprises depend on flexible working capital. SHG-bank linkage programmes, supported by NABARD, have created one of the world’s largest community-based credit ecosystems. The spread of formal rural finance has risen significantly, showing a rising share of rural households accessing institutional credit channels like KCC.

What is the modus operandi?

A normal term loan is sanctioned once and repaid in fixed instalments, but in revolving credit, which comes with a pre-approved credit limit, borrowers can draw, repay and reuse. It is like a financial buffer, allowing households, farmers and small entrepreneurs manage short-term cash needs, emergencies, and income fluctuations without applying for a fresh loan each time.

A prominent form of revolving credit in the rural areas was the KCC scheme, introduced in 1998-99 based on the recommendations of the R.V. Gupta Committee. Over time, it expanded beyond crop cultivation to allied activities such as dairy, fisheries and animal husbandry.

Latest data suggest that more than 7.72 crore KCCs are active nationwide, with outstanding loans of about ₹10.2 lakh crore, majority of the beneficiaries being small and marginal farmers.

For the lenders, revolving credit products are strategically attractive as they provide recurring income streams and better utilisation of existing credit infrastructure, as well as higher returns on assets through repeated usage, but unchecked expansion may increase delinquencies and capital requirements; implying profitability when managed with strong risk controls.

What is the role of NBFCs?

Finding the vast untapped potential and higher yield (as small-ticket unsecured revolving loans generally carry higher interest rates on higher risk), NBFCs (non-banking finance companies) have largely expanded revolving credit through consumer credit lines, digital loans, merchant finance, MSME working-capital loans and fintech partnerships.

NBFCs have emerged as an important pillar of India’s last-mile credit delivery, particularly in rural and semi-urban areas where traditional banks face challenges due to high transaction costs, lack of collateral and information asymmetry.

Per the latest data, more than 9,000 registered NBFCs are operating in India, with the vast majority in the Base Layer category, having overall outstanding credit of ₹58.61 lakh crore by mid-2026.

The rural credit footprint of NBFCs is largely driven by microfinance institutions (MFIs), gold loan companies, vehicle financiers, MSMEs and small-ticket retail lenders. Agriculture remains a relatively small component of overall NBFC lending against industry and retail segments.

The portfolio outstanding of the microfinance sector, comprising players such as NBFC-MFIs and small finance banks, stood at ₹2.77 lakh crore as at March-end 2026 compared to ₹3.35 lakh a year earlier and ₹3.78 lakh crore as at March-end 2024.

What is RBI’s concern?

The RBI’s attempt to restrict the revolving credit offered by NBFCs shows its legitimate concern as the regulatory body needs to tread a delicate balance between financial inclusion and financial stability.

To bring clarity, the RBI is proposing an amendment as it defines ‘term loan’ and ‘revolving credit’ for the first time. A term loan can be disbursed in one or more tranches, but repayment must follow a fixed schedule. Once repaid, the credit limit cannot be restored or reused. Any facility that does not meet this definition will be treated as revolving credit, which NBFCs can no longer offer.

Rising concerns around unsecured retail credit and potential debt cycles prompted the RBI to seek amendments, considering that KCC and such other instruments are essential for growth, but it viewed that unchecked and easy accessibility through digital platforms and consumer finance channels could expose it to more vulnerabilities.

The NBFC-MFIs have been among the largest providers of unsecured loans. According to the SIDBI-Equifax report, the total microfinance portfolio outstanding shrank by about 17% year-on-year to ₹2.77 lakh crore by March 2026 and geographically, the top five states (Bihar, Uttar Pradesh, Tamil Nadu, West Bengal and Karnataka) account for 57% of total portfolio outstanding.

What has the unchecked expansion led to?

Apprehensive of evergreening, RBI repeatedly flagged the rapid growth of unsecured retail credit, particularly through fintech–NBFC partnerships, offering high-risk loan products as revolving credit lines.

The latest Economic Survey acknowledges the NBFC’s critical role in inclusion but warns that unchecked expansion can weaken household balance sheets.

However, the RBI remained sceptical of certain forms of revolving credit offered by non-bank entities, particularly where repayment patterns could conceal a rise in household indebtedness.

The RBI’s concerns were not only on the tenuous boundary between lending and technology but also on that technology has made borrowing easier and faster than financial discipline.

Multiple borrowing through various apps and lack of due diligence without effective credit information sharing have elevated risks. Some digital platforms relied on algorithms and alternative data without sufficient assessment of repayment capacity, indicating weak underwriting.

Unlike agricultural or business revolving credit, many digital credit lines financed consumption rather than income-generating activities.

What is the path forward?

A blanket restriction may be counterproductive as the MFI space has historically been underserved, with lending remaining muted due to asset quality pressures and limited funding access.

The policy challenge is not to curb NBFC innovation but to identify credit that helps in income generation because excessive regulatory tightening may push borrowers back towards informal lenders, defeating the very purpose of financial inclusion.

Long-term sustainability, it suggests, depends more on how responsibly credit is delivered than how fast it grows.

Robust borrower profiling, credit bureau integration, responsible lending norms and limits on multiple exposures would go a long way in addressing the credit needs and mitigating the risks, particularly in the rural sector.

Source link

Business

Post navigation

Previous Post: CM Abdullah rules out raising internal issues with U.S. Ambassador Sergio Gor
Next Post: Sugar power: the full story of brain development in humans

Related Posts

  • Access Denied Business
  • Access Denied Business
  • Petronet LNG’s revenues slip more than 50% as West Asia tensions marred supplies
    Petronet LNG’s revenues slip more than 50% as West Asia tensions marred supplies Business
  • Access Denied Business
  • Indian economy to record high growth despite volatile external environment: RBI Governor
    Indian economy to record high growth despite volatile external environment: RBI Governor Business
  • Yes Bank co-founder Rana Kapoor gets bail in bank fraud case after four years
    Yes Bank co-founder Rana Kapoor gets bail in bank fraud case after four years Business

More Related Articles

Rupee trades in narrow range against US dollar in early trade Rupee trades in narrow range against US dollar in early trade Business
Something big soon on India, says Hindenburg Research Something big soon on India, says Hindenburg Research Business
GST 2.0: M&M passes on full GST benefits from today, XUV3XO diesel becomes cheaper by ₹1.56 lakh GST 2.0: M&M passes on full GST benefits from today, XUV3XO diesel becomes cheaper by ₹1.56 lakh Business
Maruti Suzuki cuts prices of select trims of Alto K10, S-Presso Maruti Suzuki cuts prices of select trims of Alto K10, S-Presso Business
Government imposes minimum export price of 0 per tonne on onion till December 31 Government imposes minimum export price of $800 per tonne on onion till December 31 Business
Vodafone Idea FPO worth ₹18,000 to open from April 18 Vodafone Idea FPO worth ₹18,000 to open from April 18 Business
SiteLock

Archives

  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2022
  • November 2022
  • October 2022
  • September 2022
  • August 2022
  • July 2022
  • June 2022
  • May 2022

Categories

  • Business
  • Nation
  • Science
  • Sports
  • World

Recent Posts

  • Why CJI Surya Kant said ‘no’ to Rahul Gandhi’s request to meet | Explained
  • Frankfurt-Delhi Air India flight diverted to Jaipur following bomb threat
  • U.S. judge backs CNN, MS Now, Politico access to White House
  • India urges UN human rights mechanisms to avoid politicisation, selectivity
  • Saudi says Houthi attacks sparked Aramco fire, wounded 4 in Riyadh

Recent Comments

  1. RobertTes on UP Teacher Who Asked Students To Slap Muslim Classmate
  2. Manuelret on UP Teacher Who Asked Students To Slap Muslim Classmate
  3. RobertTes on UP Teacher Who Asked Students To Slap Muslim Classmate
  4. RobertTes on UP Teacher Who Asked Students To Slap Muslim Classmate
  5. BrentWes on UP Teacher Who Asked Students To Slap Muslim Classmate
  • Access Denied
    Access Denied Nation
  • UN Chief Hopes PM Modi’s Visit To Ukraine Will Help End War
    UN Chief Hopes PM Modi’s Visit To Ukraine Will Help End War World
  • Access Denied Sports
  • Class 10 And 12 Students In Relief Camps Get Help From Manipur Scientists, Academicians Group PIMMSAA
    Class 10 And 12 Students In Relief Camps Get Help From Manipur Scientists, Academicians Group PIMMSAA Nation
  • Donald Trump defends Russia diesel deal as lawmakers from both parties complain
    Donald Trump defends Russia diesel deal as lawmakers from both parties complain World
  • Cats are killing India’s birds. Are we paying attention?
    Cats are killing India’s birds. Are we paying attention? Science
  • FM proposes hike in STT on F&Os to discourage retail participation
    FM proposes hike in STT on F&Os to discourage retail participation Business
  • Observations by Aditya-L1 help decode unusual dawn-time geomagnetic disturbances during strong solar storms
    Observations by Aditya-L1 help decode unusual dawn-time geomagnetic disturbances during strong solar storms Science

Editor-in-Chief:
Mohammad Ariff,
MSW, MAJMC, BSW, DTL, CTS, CNM, CCR, CAL, RSL, ASOC.
editor@artifex.news

Associate Editors:
1. Zenellis R. Tuba,
zenelis@artifex.news
2. Haris Daniyel
daniyel@artifex.news

Photograher:
Rohan Das
rohan@artifex.news

Associate Journalists
1. Subrata Paul - AN/2020/01
2. Quamruz Zaman - AN/2021/22
3. Ahmed Sha - AN/2021/035
4. Ajay Kumar Shaw - AN/2021/39
5. Tahqiqul Hoda - AN/2021/21

Artifex.News offers Online Paid Internships to college students from India and Abroad. Interns will get a PRESS CARD and other online offers.
Send your CV (Subjectline: Paid Internship) to internship@artifex.news

Links:
Associate Journalism
About Us
Privacy Policy

News Links:
Breaking News
World
Nation
Sports
Business
Entertainment
Lifestyle

Registered Office:
72/A, Elliot Road, Kolkata - 700016
Tel: 033-22277777, 033-22172217
Email: office@artifex.news

Editorial Office / News Desk:
No. 13, Mezzanine Floor, Esplanade Metro Rail Station,
12 J. L. Nehru Road, Kolkata - 700069.
(Entry from Gate No. 5)
Tel: 033-46011099, 033-46046046
Email: editor@artifex.news

Copyright © 2023 Artifex.News Newsportal designed by Artifex Infotech.