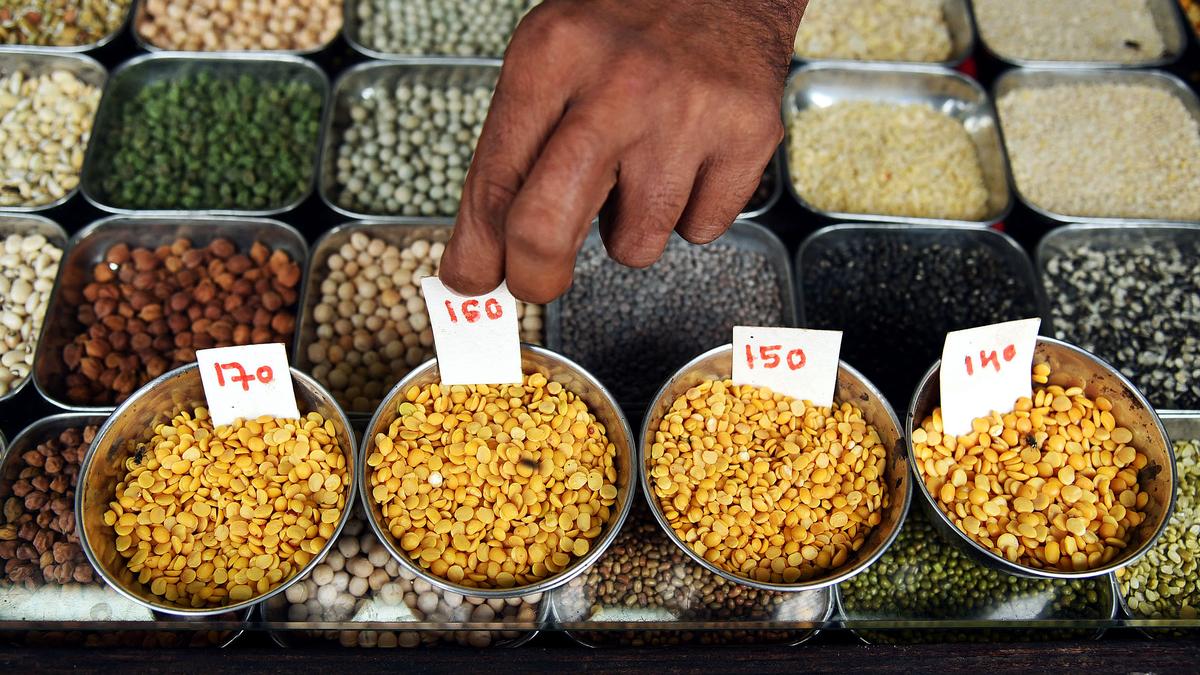



A customer picks a product from a rack at a supermarket in India (For Illustration)
| Photo Credit: Reuters
India’s fast-moving consumer goods (FMCG) sector is expected to report relatively stable earnings for the September quarter (Q2FY27), supported by pricing actions and resilient demand. However, rising commodity costs are likely to squeeze margins, while volume growth is expected to moderate, according to an earnings preview by Elara Capital.
FMCG volume growth is projected to ease to 9% from 9.5% in the preceding quarter. Gross margins are expected to contract by 51 basis points, reflecting higher input costs and expensive inventory.
Commodity inflation clouds outlook
Input cost pressures remained elevated during the quarter, with milk and sugar prices rising 3% and 18% year-on-year (YoY), respectively. Palm oil prices increased 21% YoY. Crude oil prices were also reported to be 47% higher YoY.

Higher commodity prices could prompt further price increases, potentially weighing on consumption. Companies’ ability to pass on costs without compromising volumes will be crucial to protecting profitability.
HUL sees steady growth
Hindustan Unilever (HUL) is expected to report 11% revenue growth in Q2FY27, with volume growth projected at 6%. Home care is likely to remain a key growth driver, with the segment expected to expand nearly 14%.
Earnings before interest, tax, depreciation and amortisation (EBITDA) are projected to grow 7% YoY, while margins could contract by 80 basis points to 23%, reflecting cost pressures.
ITC grapples with cigarette tax impact
ITC’s cigarette business is expected to face volume pressure following the excise duty hike and subsequent price increases. Cigarette gross revenue is projected to rise 74%, while net sales are expected to decline 20%, with volumes estimated to fall 8%.
The divergence reflects the impact of higher taxation on reported segment revenue and sales, alongside pricing adjustments undertaken to offset the additional burden.

Britannia gets a favourable base
Britannia Industries is expected to post 13.5% YoY growth in net sales, aided by a favourable base following just 3.7% growth in the year-ago quarter.
Volume growth is projected at 10%, against a 3% decline in Q2FY26. Price increases and a better product mix are expected to support realisations amid elevated input costs.
External risks persist
Geopolitical tensions in West Asia could fuel further crude oil volatility, raising packaging and transportation costs. Domestically, elevated inflation and uneven monsoon distribution could weigh on rural demand. The potential impact of El Niño on rainfall patterns adds to the uncertainty.
Published – October 15, 2026 04:06 pm IST